New PayID Pokies in Australia: Payment Guide
 Available in AU
PayID identifies a bank transfer, but it is not a wallet and does not establish how a pokies site handles deposits or withdrawals.
Table of Contents
- How PayID Fits Into Online Pokies Payments
- Paying In: Limits, Minimums and Bank Blocks
- PayID Pokies in Australia: What the Payment Method Does—and Doesn’t—Tell You
- Before You Use PayID at a New Pokies Site
- Comparing PayID Payouts Without Trusting the Hype
- Real-Money Terms: Withdrawal Costs and Bonus Conditions
How PayID Fits Into Online Pokies Payments
PayID is a way to identify a bank payment without relying on the usual string of account details. The identifier can be something already linked to the user’s bank account, such as a mobile number or email address. Behind that simple label is the New Payments Platform (NPP), which connects participating banks so money can move between them quickly.
When a
The important distinction is that PayID is the identifier and transfer method; it is not a separate wallet holding a balance. The money comes from the bank account used to make the payment and is sent through the bank network. That can make the process feel familiar if you have used PayID for other transfers. No extra account with PayID itself is needed.
If you’re looking at new PayID pokies in Australia, check what is actually documented before choosing a site. These verdicts stick to the available operator details and do not confirm PayID availability.
License: Curacao eGaming (Roby Games Ltd) Roby Casino is listed with a Curacao eGaming license held by Roby Games Ltd. The available details do not specify PayID support.
License: Curacao eGaming OGL/2023/174/0082 (Dama N.V.) · Min. deposit: A$15 LevelUp Casino lists a Curacao eGaming OGL/2023/174/0082 license held by Dama N.V. Its minimum deposit is A$15; PayID availability is not specified.
License: Curacao – Antillephone N.V. (Versus Odds B.V.) · Min. deposit: EUR 20 Thor Casino lists a Curacao – Antillephone N.V. license held by Versus Odds B.V. Its minimum deposit is EUR 20, while PayID availability is not specified.
Payout speed: crypto 30-120 minutes, fiat 24-72 hours · Min. deposit: A$30 MrPacho lists a minimum deposit of A$30. Its stated payout speeds are 30–120 minutes for crypto and 24–72 hours for fiat; PayID availability is not specified.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Neospin lists a Curacao Gaming Control Board OGL/2023/176/0095 license held by Hollycorn N.V. The available details do not specify PayID support.
License: Curacao Gaming Control Board (TechSolutions Group N.V.) Bizzo Casino lists a Curacao Gaming Control Board license held by TechSolutions Group N.V. The available details do not specify PayID support.
License: Curacao Gaming Control Board OGL/2023/176/0095 (Hollycorn N.V.) Rollero Casino lists a Curacao Gaming Control Board OGL/2023/176/0095 license held by Hollycorn N.V. The available details do not specify PayID support.
License: Curacao Gaming Authority (Jumpman Gaming Ltd) DragonSlots Casino lists a Curacao Gaming Authority license held by Jumpman Gaming Ltd. The available details do not specify PayID support.
License: Curacao Golden Pokies is listed with a Curacao license. No further operator details or PayID information are provided.
License: Curacao OGL/2024/1335/0780 · Min. deposit: EUR 20 Vegaz Casino lists a Curacao OGL/2024/1335/0780 license and a minimum deposit of EUR 20. The available details do not specify PayID support.
What happens after you start a deposit
The payment flow generally has two sides: the payment page requests a transfer, and the bank handles the actual movement of funds. You choose PayID as the displayed option, follow the instructions provided for that payment, then complete the transfer through your bank. The bank processes the payment across the NPP, and the receiving side can update the balance once it has registered the incoming funds.
That last step matters. Pressing a button on a payment page is not the same thing as the money having arrived. The bank must process the transfer, and the receiving system must recognise it. With PayID, deposits at online casino payment pages are typically completed within seconds, but the visible balance may depend on the receiving side updating correctly. A short pause on the screen does not, by itself, tell you that the payment failed.
I used to treat any delay as a reason to start the whole process again. That was a bad habit. If you have already authorised a transfer, first check your bank’s transaction record and the payment status shown on the page. Sending a second payment before you know what happened can leave you with two transfers to sort out rather than one. Keep the confirmation screen or transaction record until the balance has updated.
Why the identifier matters
A PayID points to a destination using a recognisable identifier, rather than making you rely only on a long bank account number. That can reduce the amount of detail you need to type, but it does not remove the need to read what is on screen. A phone number or email address is useful only if it is the intended identifier for that payment.
Before authorising anything, compare the payment instructions on the page with the destination shown in your banking flow. If the details do not line up, stop rather than guessing. The identifier is part of routing the transfer; it is not a description of what the payment is for, nor proof that the receiving service has handled it correctly.
This is also why PayID should not be thought of as an instant “top-up” button. The action still involves a bank transfer. Your bank is the place where you confirm and make that transfer, while the payment page is where the receiving service can show whether it has credited the deposit. Those are related stages, but they are not the same screen or the same system.
Quick transfer, separate confirmation
The NPP is designed to facilitate quick transfers between banks, which is why PayID can be much faster than methods that rely on slower processing. In this payment flow, the bank-to-bank movement is the central piece. The payment page does not make the transfer happen merely by displaying a PayID option; the user still needs to complete the bank-side action.
Once the transfer is authorised, give the receiving balance a moment to reflect it. If the bank shows the payment as sent but the page has not changed, avoid repeating the transfer immediately. Check the displayed status and use the service’s stated payment-support route if the mismatch persists. I’ve learned that a calm check beats clicking through the same payment twice.
- Check your bank’s transaction record if the balance doesn’t update
- Keep the confirmation screen until the balance has updated
- Compare payment instructions with the destination in your banking flow
- Start the payment process again if there is a short pause
- Send a second payment before knowing the status of the first
- Guess the destination if the details do not line up
PayID’s role is narrow but useful: it gives a bank transfer a simple identifier and lets the NPP carry it between banks quickly. The interface around it may vary, but the core sequence remains recognisable: choose the method shown, follow the bank’s transfer steps, and allow the receiving side to register the deposit. That is the payment mechanics—not a promise about anything beyond the transfer itself.
Paying In: Limits, Minimums and Bank Blocks
The deposit amount you can send is governed by two separate ceilings: the minimum set by the payment destination and the transfer limit applied by your bank. They are easy to mix up. A payment can meet the stated minimum and still be declined because it exceeds your personal PayID limit, or because the bank does not allow that recipient.
The minimum is set at the other end
PayID does not create one universal deposit minimum. The amount accepted depends on the operator’s own payment terms. A specialist review describes common starting deposits as AU$10 to AU$20, while reporting that some operators list AU$5 as the minimum. Treat those figures as reported terms, not a promise that a particular cashier will accept them. Minimums can differ between services and may change.
I’ve learned not to assume that the smallest figure mentioned in a headline will appear in the payment screen. The useful number is the minimum actually displayed for the PayID option before you try to send anything. If the stated minimum is higher than the amount you intended to transfer, stop and check the terms rather than sending a smaller amount and hoping it will be credited.
A minimum is not a recommendation about how much to deposit. It only describes the amount a payment destination says it will accept. Keeping that distinction clear matters: a low entry point can sound like a nudge to try it, but the figure itself says nothing about whether a service is appropriate, lawful or reliable. No magic number.
Your bank’s limit is separate
The maximum you can send through PayID is not necessarily set by the payment destination. A specialist review reports that the daily transfer limit is set by the customer’s bank. The limit attached to your account is the one to check; another person’s limit, or a limit mentioned in a general guide, may not apply to you.
If a transfer is rejected for being over your limit, sending the same amount again is unlikely to solve the problem. Check your bank’s PayID settings or contact the bank to understand the limit attached to your account. Do not assume that a transfer limit can be raised instantly, or that your bank will approve a request to change it. The bank controls that decision.
It also helps to distinguish a daily limit from the amount available in your account. Having enough money in the account does not necessarily mean the transfer will fit within the bank’s PayID limit. Conversely, a transfer within that limit can still be declined for another reason. A rejected payment does not, by itself, tell you which limit or policy was responsible.
Attention Having enough money in your account does not guarantee a transfer will fit within your bank’s PayID limit.
When the bank blocks the transfer
A specialist review reports that some Australian banks, including members of the Big Four, have at times blocked PayID transfers to known gambling merchants under their acceptable use policies. That is a report of a possible restriction, not a statement that every bank blocks these payments or that a block is in force for every customer. Bank policies and how they are applied can change.
If your bank declines a payment, check the message it provides and ask the bank what restriction applies. A declined transfer may reflect a bank policy rather than an error in the amount you entered. Don’t keep resending it or try to disguise the recipient to get around a block. That can create further problems with the bank and does not make the underlying restriction disappear.
The practical point is simple: a PayID option being shown by a payment destination does not mean your bank will permit a transfer to it. The bank has its own rules, and the final decision is not something the payment destination controls.
A sensible check before sending
Before making any payment, compare the destination’s stated minimum with your bank’s PayID limit and the amount you intend to send. If either figure is unclear, pause and get an answer from the relevant party: the destination for its minimum, the bank for its transfer limit or a declined payment. Guesswork is a poor way to handle a bank transfer.
Pay attention to the exact amount and recipient shown before confirming. If the bank declines the transaction, use its explanation rather than repeatedly changing the amount at random. If the stated minimum is the obstacle, do not send a smaller transfer on the assumption that it will be held or credited later; the payment terms may not provide for that.
These checks won’t make a blocked payment go through, and they cannot override a bank’s policy. They do help separate three different issues: the minimum requested by the destination, the daily limit applied by the bank, and any restriction the bank places on the recipient. When one of those does not line up, stopping is safer than improvising.
PayID Pokies in Australia: What the Payment Method Does—and Doesn’t—Tell You
PayID has a straightforward role in Australian banking: it lets people send money using an identifier such as a mobile number or email address, rather than entering a bank account number and BSB. It works through the New Payments Platform (NPP), which supports quick transfers between banks. That can make PayID feel like a natural fit wherever a payment page offers it.
The useful part is the payment method itself. PayID transfers can move quickly, and PayID does not charge a transfer fee. Reputable venues also do not add a separate fee simply for using PayID to deposit or withdraw. Those are practical advantages, but they describe how a payment channel works. They do not tell you what kind of business is on the other end.
That distinction matters with
Legal Warning
Under the Interactive Gambling Act 2001, it is illegal for operators to provide real-money online casino games to people physically located in Australia.
Australian context matters
The legal position is unusually important here. Under the Interactive Gambling Act 2001, it is illegal for operators to provide
So a site describing itself as “Australian-friendly” is making a claim about access, not establishing that it can lawfully provide online casino games to people in Australia. Likewise, an Australian payment option does not change the legal status of the service. The transfer system and the gambling service are separate things.
I used to read a familiar payment option as a quiet sign that a site was more established. That was a poor shortcut. A recognised payment method can tell you something about how money is moved, but not whether the merchant is trustworthy or legally entitled to offer the activity. The logo does not do the checking for you.
Quick transfer, limited meaning
The NPP’s role is to facilitate quick bank-to-bank payments. In a payment flow, that can mean the money moves rapidly once the transaction is accepted. It does not mean every part of an online casino transaction is equally fast, nor does it guarantee what happens after money reaches a business. A payment rail can carry a transfer; it cannot certify the business receiving it.
The same limit applies in the other direction. PayID supports transfers both to and from accounts, but a method’s ability to carry money back does not prove that a particular venue will approve or send a withdrawal. There is a difference between a payment option being technically capable of receiving funds and a business being willing or able to return them.
That difference gets blurred by words such as “instant” or “secure”. “Instant” describes the transfer experience, not the whole relationship with a merchant. “Secure” describes a feature of the payment system, not a guarantee that every organisation displaying PayID is fair. Marketing language often compresses those separate questions into one reassuring impression. I try to pull them apart.
A fee-free method is not a fee-free promise
PayID itself does not impose a transfer fee. Reputable venues also do not add a PayID-specific charge for deposits or withdrawals. That is useful to know when comparing payment methods, but it should not be stretched into a claim that every transaction connected with a casino will be free of costs. A payment method’s own fee policy is narrower than the venue’s full set of terms.
Nor does a lack of PayID fees make a service safe or suitable. A transaction can be quick and carry no PayID charge while still involving a recipient whose status and conduct are separate concerns. Those are not contradictory facts; they answer different questions.
For me, the practical takeaway is modest: PayID can offer quick transfers between banks without charging its own transfer fee. It does not provide a shortcut for judging a gambling site. If a page uses PayID as proof that it is legitimate, fair, approved or certain to pay, it is asking the payment method to prove things it cannot prove.
That’s the dividing line. PayID tells you about the transfer channel. It does not validate the gambling service, and it does not change the Australian law governing operators that offer real-money online casino games to people here. No endorsement implied.
Key Takeaways
- PayID is a transfer channel and does not validate the legitimacy of a gambling site
- A recognized payment method is not a regulatory stamp or a guarantee of fairness
- The NPP facilitates quick transfers but cannot certify the business receiving the funds
- No PayID transfer fees do not equal a fee-free experience with the venue
Before You Use PayID at a New Pokies Site
A site saying it accepts PayID is making a statement about a payment option. It is not proof that the site is lawful, fair, or prepared to pay out. That distinction matters in Australia: the Interactive Gambling Act 2001 prohibits operators from providing real-money online casino games, including pokies, to people physically in the country. A payment logo does not change that.
I would treat a new site’s payment claim as something to scrutinise, not an invitation to sign up or send money. There is a particular trap in
Pause before authorising a transfer
The most important practical point is that a confirmed PayID transaction cannot be reversed. That makes the moment before confirmation more important than any reassuring wording on a page. If the recipient details look unexpected, the amount is wrong, or you are unsure who will receive the money, do not confirm the transfer. A quick payment is not a reason to rush.
I would not rely on a site’s own description of its cashier as independent confirmation. A page can say “instant,” “secure” or “verified”; those are claims, not safeguards. Read the recipient details shown in your banking app and compare them with the instructions you were given. If they do not line up, stop rather than guessing which detail is harmless.
This is different from the normal deposit flow. The flow explains how a payment is submitted and credited. The check here is whether you should authorise a transfer to this recipient at all. Once confirmed, there is no undo button built into PayID.
Check first. Send second.
Make sure the PayID belongs to you
PayID details need to match the PayID registered with your bank. If you use a mobile number or email address as your identifier, make sure it is the one your bank has registered, rather than a different contact detail you happen to use elsewhere. A mismatch can create trouble before a transfer is even considered complete.
Also check that the account name you use is consistent with the name on your profile. I would not assume that a site can sort out a mismatch later, or that support can simply redirect a payment. Keeping names and details consistent is a basic way to avoid preventable payment confusion, especially if a site later asks you to verify who owns an account.
Be careful about requests to use another person’s PayID or bank account. That changes who appears to have made the payment and can make it harder to explain or trace what happened. If you cannot use your own registered details, that is a reason to pause—not a reason to improvise.
Don’t let a payment option stand in for due diligence
PayID’s presence on a page does not establish that an operator is licensed in Australia or that its games are fair. Nor does it mean that a site will honour a withdrawal. Those are separate claims, and the payment method cannot settle them.
For people in Australia, the legal position is especially important: providing real-money online casino games to customers physically located here is prohibited under the Interactive Gambling Act 2001. That includes pokies. I would not interpret a local-sounding payment option, Australian currency, or familiar banking language as evidence that a real-money casino service is permitted.
There is no need to send a small “test” payment to find out whether a site’s PayID works. A small transfer is still a confirmed transfer, and the irreversibility applies regardless of how much you send. If the site pressures you to pay quickly, changes the recipient details, or asks you to ignore a mismatch, those are reasons to walk away from the payment request.
Keep a record, but don’t mistake it for protection
If you have already authorised a transfer, keep the transaction record and any messages or payment instructions connected with it. That can help you explain what happened if you need to contact your bank. It does not make a confirmed PayID payment reversible, and it does not guarantee that the recipient will return the funds.
I used to think a familiar payment method made a transaction feel safer. That was the wrong shortcut. The useful check is much narrower: are the PayID details actually yours and correctly registered with your bank, and do the recipient details match what you intended to pay? If either answer is uncertain, do not confirm. A payment option is not a seal of approval.
Comparing PayID Payouts Without Trusting the Hype
A payout claim can sound simple: request the money, receive it
I used to read “fast withdrawals” as if the payment method controlled the whole journey. That was the wrong bit to focus on. A withdrawal has separate stages: the request is checked, it may sit in a pending period, the casino approves and sends it, and the transfer then reaches the bank account. A delay before approval is not a PayID transfer delay.
Separate the review from the transfer
The casino may review a withdrawal internally and check the account’s
That distinction matters when comparing claims. “Paid by PayID” tells you the stated transfer route; it does not tell you when a request will be reviewed, whether it will be held pending, or when approval will be given. Those are separate questions. Keep them separate. It saves confusion.
A specialist review reports that casino-initiated PayID withdrawals may remain pending for 24–72 hours before funds leave the casino’s system. Treat that as a reported practice, not a universal timetable: a pending period is set on the casino side, and the stated range does not guarantee how a particular request will be handled.
Payout Timelines
Casino-initiated PayID withdrawals may remain pending for 24–72 hours before the funds actually leave the casino’s system.
The same kind of review describes PayID transfers after approval as taking 12–24 hours, while putting the full wait from request to receipt at 2–4 days when an internal pending period is included. These are reported estimates, not a promise about any individual payout. The key is the starting point: a transfer-time figure measured from approval does not include time spent waiting for approval.
Read the start and end points
When a payout claim gives a time, check what event starts the clock. Is it measured from submitting the withdrawal, from completing account checks, or from approval? Those are not interchangeable. A claim about how quickly a transfer arrives after approval cannot tell you how long the preceding review will take.
Also look for a clear description of what “processed” means. It might mean the request has entered a queue, passed an internal check, or actually been sent. If the wording does not identify the stage, it is hard to compare with another claim. “Instant” is especially unhelpful without that context. Instant what?
A specialist review also reports that PayID transfers may reach the account on the same day once the casino has approved them. That describes the post-approval stage; it does not remove the possibility of an earlier review or pending period. I would not turn that statement into a guaranteed arrival time.
What a fair comparison can tell you
To assess a payout claim, look for the steps and conditions behind it rather than treating a single headline time as the whole process. A useful explanation distinguishes casino review from payment transfer, says when its clock begins, and makes clear that account checks can affect approval. If a claim leaves those points vague, it gives you little basis for estimating the wait.
Even a detailed claim remains a description of reported handling, not a guarantee. The internal review, the account’s verification status and the casino’s own process can all affect the timeline. The payment method alone cannot settle those questions. Quick rails, slow gate.
I also avoid reading one reported timeframe as proof that every request follows it. The pending-period and overall-wait figures come from specialist-review reporting, so they are best understood as examples of how the stages can add up—not as a fixed service standard. A particular request may not match them.
Most importantly, payout speed is not a measure of whether a site is lawful, fair, or willing to pay. A polished payment claim can only describe what the claim says about processing; it cannot establish those broader things. I no longer treat a fast-method label as a verdict. It is one small part of a much longer chain.
Real-Money Terms: Withdrawal Costs and Bonus Conditions
“Real money” describes what is at stake, not what you are guaranteed to receive. A balance shown on a screen can be subject to withdrawal rules, deductions and bonus conditions. I learned to read those terms as part of the amount, not as small print I could sort out later.
There is also a legal point that matters in Australia: under the Interactive Gambling Act 2001, providing real-money online casino games, including pokies, to people in Australia is illegal. This is not a recommendation to use an offshore service. The details below explain how payment terms can affect a balance; they do not make such a service lawful or establish that it will pay.
Typically in the AUD 20–50 range, though specific terms vary by service.
Some services deduct A$5–A$10 for small withdrawals or charge AUD 2–5 per transaction.
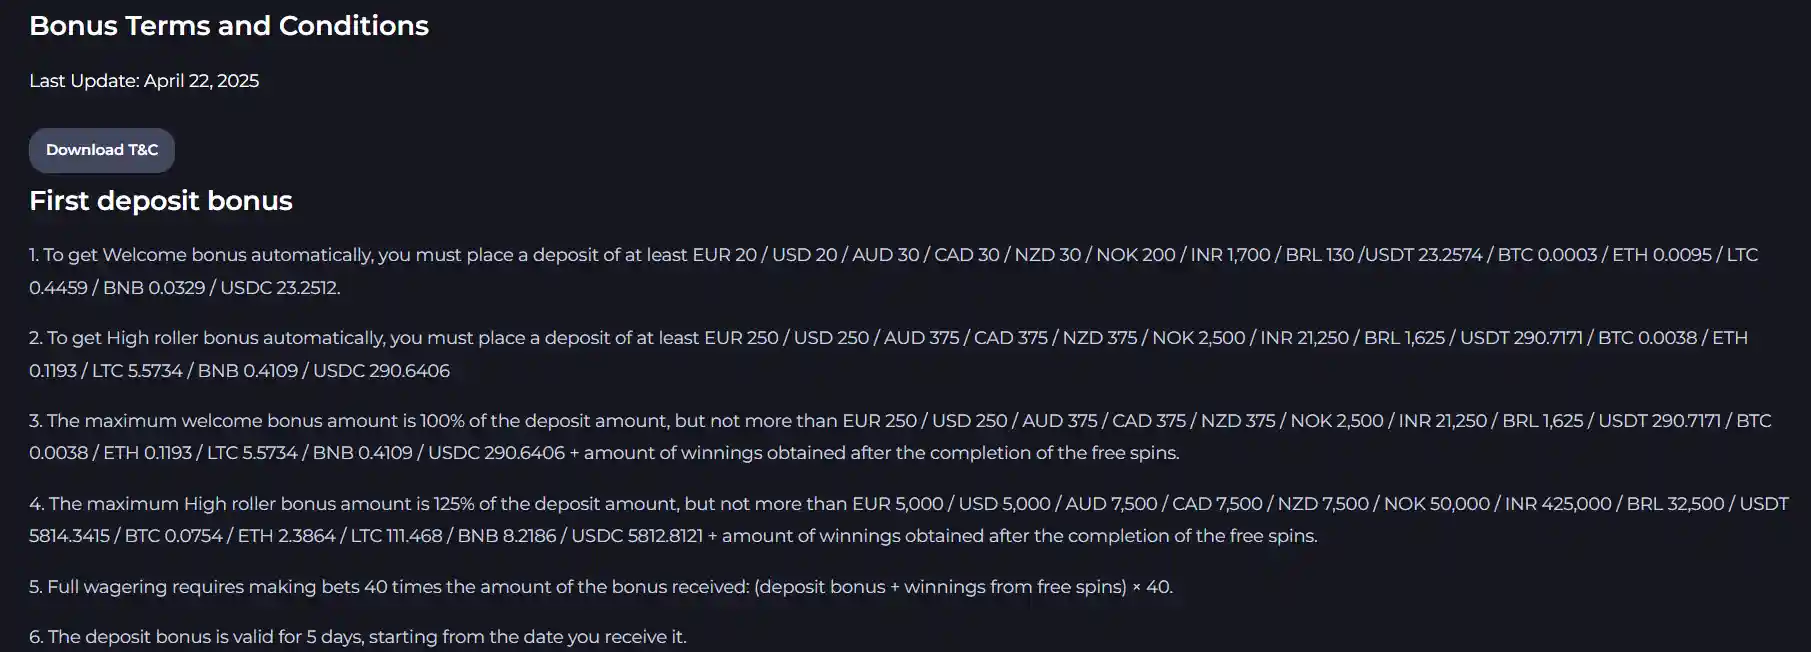
Bonus funds often require 30x–45x wagering before they can be withdrawn.
The amount you can request
A displayed balance and a withdrawable balance may not be the same thing. A minimum withdrawal is the smallest amount a service says it will process. A specialist review reports PayID withdrawal minimums in the AUD 20–50 range, but an individual set of terms may differ. The relevant figure is the one stated in the service’s own withdrawal rules, not an amount inferred from its payment page.
That distinction can matter when a balance sits below the stated minimum. A player may have funds showing in an account without being able to request them through that method yet. The minimum can also shape how much is left after a withdrawal, so it is worth checking the rule before treating the full displayed balance as cash available to you.
The payment method and the service’s charges are separate issues. PayID itself does not charge a transfer fee. That does not mean every service handles withdrawals without a deduction: a service may set its own conditions, and those need to be read separately from the payment system’s fees.
Deductions and fees
A specialist review reports that some services deduct A$5–A$10 from withdrawals below internal thresholds, with A$100 or A$200 cited as threshold examples. These are reported terms, not a rule that applies everywhere. Another specialist review reports that some casinos charge AUD 2–5 per withdrawal. Again, neither figure should be assumed to apply to a particular service without seeing its current terms.
I used to focus on the amount I could request and ignore what might be taken off it. That was backwards. Check whether a fee is charged per withdrawal, whether a deduction depends on the amount requested, and whether the service distinguishes between a standard processing charge and a threshold-based deduction. Those are different conditions, even when both reduce what reaches an account.
If a term is unclear, do not fill the gap with a guess. Look for the exact wording in the withdrawal rules and cashier information, and keep a copy of the terms shown when the request is made. A payment label alone does not explain what the service may subtract.
Bonus conditions change the calculation
A bonus is not necessarily withdrawable as soon as it appears in a balance. A specialist review reports wagering requirements of 30x–45x the bonus amount. That means the terms may require qualifying wagers to reach a stated multiple before bonus-related funds can be withdrawn. The particular calculation can depend on the offer’s wording, so the multiple alone does not tell you the full condition.
Read what counts towards wagering, what is excluded, and whether the requirement applies to the bonus, the deposit, or a combined amount. Also check whether there is a deadline or a maximum bet condition in the terms; do not assume that all offers use the same rules. Exceeding a bonus’s maximum bet limit during wagering can void the bonus and associated winnings. That is a costly detail to miss.
A large headline bonus can look like extra value until you account for the conditions attached to it. I have made the mistake of treating a bonus balance as if it were already mine. It was not. The practical question is not just how much is displayed, but what must happen before any part of it becomes withdrawable and what conduct could cancel it.
Read the terms as a whole
Withdrawal minimums, possible fees and bonus rules can interact. A balance may be subject to a wagering requirement and still need to meet a separate minimum before a withdrawal can be requested. A fee or deduction can then affect the amount received. Reading each line in isolation makes it easy to miss how one condition changes the result of another.
Before making any financial decision, check the current withdrawal and bonus terms together. If the conditions are vague, contradictory or difficult to locate, do not rely on an advertising claim to resolve them. “No fees” is only useful if the terms explain what is fee-free; “bonus” does not mean unrestricted funds. The wording is the real deal.
Do online casino sites in Australia use PayID?
Yes, some online casino sites offer PayID for deposits. It uses your bank’s PayID service to send a transfer through the New Payments Platform.
How do you deposit money into online casino sites using PayID?
Select PayID on the payment page, follow the displayed transfer instructions, then authorise the payment through your bank. Check the recipient details before confirming, and wait for the casino balance to update before considering another transfer.
How do you set up PayID for pokies sites?
You don’t need a separate PayID account with the pokies site. Use a PayID identifier, such as your mobile number or email, that is registered with your bank, then follow the site’s payment instructions.
What is the minimum amount you can deposit into casino sites using PayID?
Minimums are set by the operator: common starting amounts are AU$10–AU$20, though some accept AU$5. Check the minimum shown for PayID in the cashier before sending money.
What security measures are in place at casino sites that use PayID?
PayID transfers are handled through your bank and the New Payments Platform, and PayID is described as a secure way to transfer money. Before authorising a payment, check that the recipient details in your banking flow match the instructions shown on the payment page.
What is the key benefit of using PayID pokies?
PayID can make deposits quick, typically completing within seconds, and uses a recognisable identifier such as a mobile number or email instead of requiring you to enter long bank account details.
Written by the editors at JeetCity Casino.